

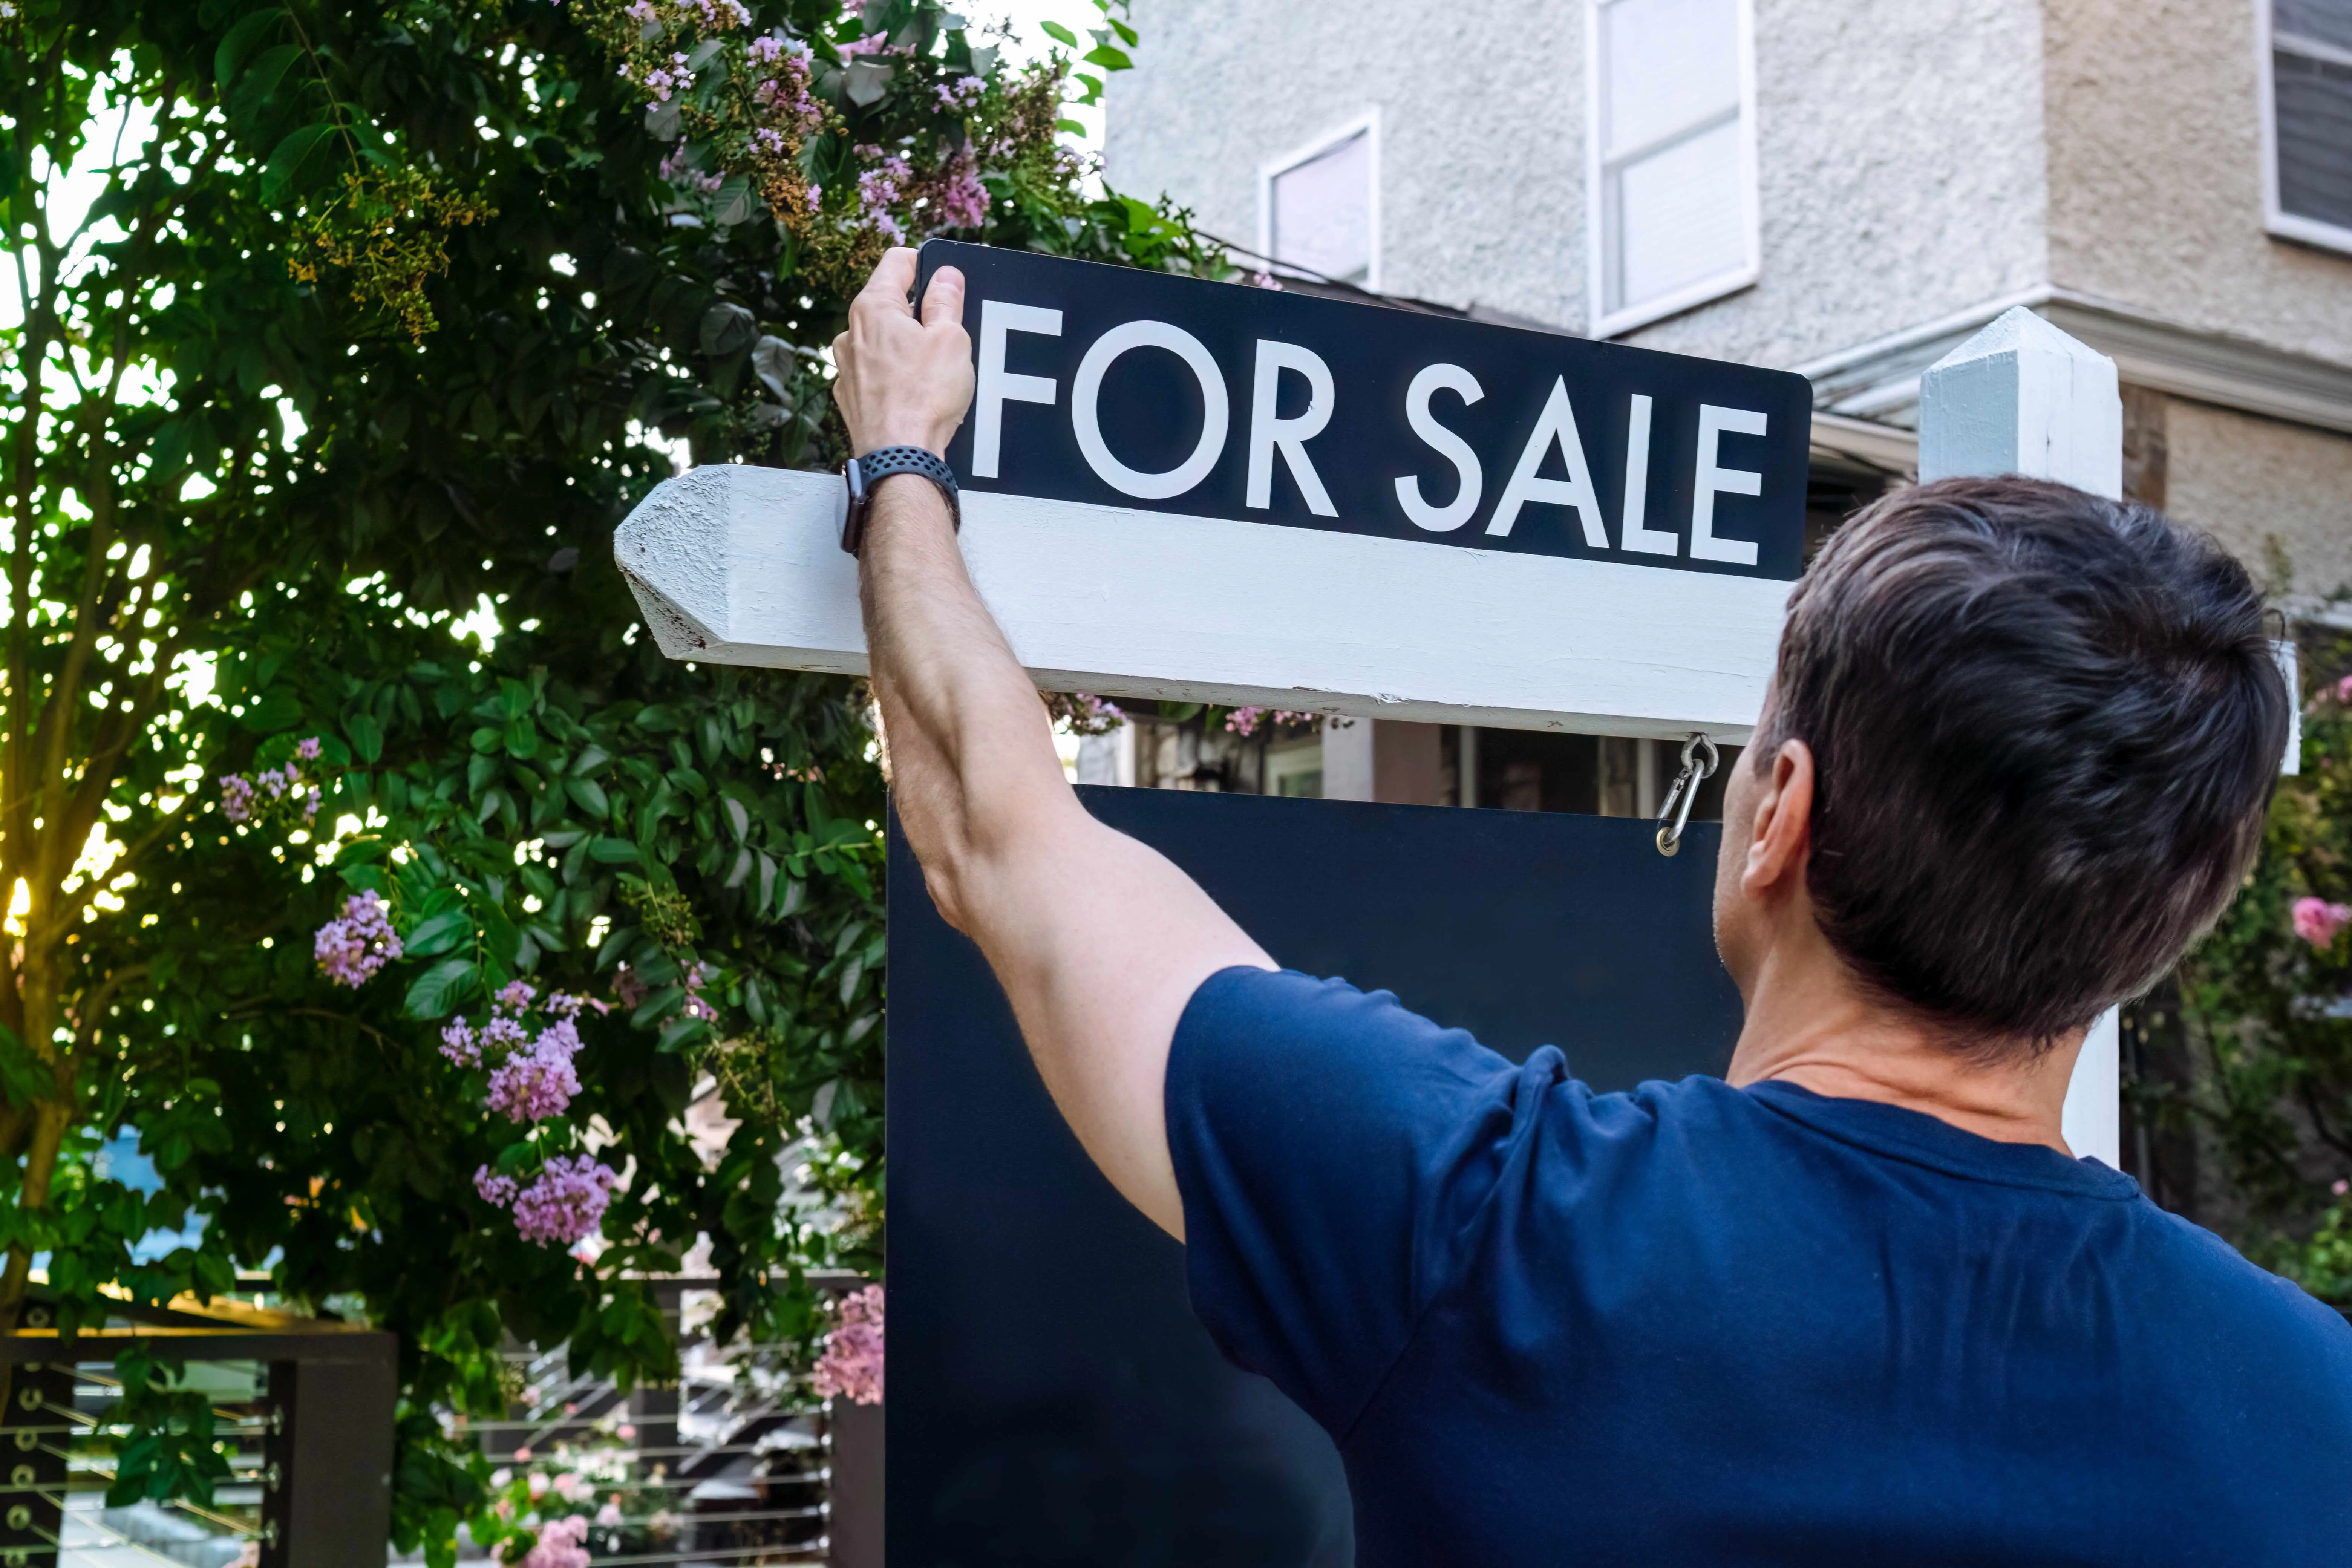
You’ve listed your home, put up the “For Sale” sign, and started planning for what’s next. But when showings slow down or offers aren’t coming as quickly as you expected, it can feel like your plans are suddenly on pause.
If your home is taking longer to sell, you’re not alone. And the good news is you may have more options than you realize. Whether you’ve already found your next home or are just starting to think about a move, understanding your choices can help you move forward with confidence.
Here are a few ways to keep your plans moving, even if your home sale is taking longer than expected.
1. Take another look at the price, condition, and presentation.
If your home has been on the market for a while, it may be worth revisiting a few key factors with your real estate agent:
Revisit your asking price. Markets can shift, and buyer expectations can change. Looking at recently sold homes in your area can help determine whether your current asking price is still competitive. A small adjustment could help attract new interest.
Look at your home through the buyer’s eyes. Sometimes, simple updates can go a long way. Fresh paint, minor repairs, updated lighting, and improved curb appeal can help buyers picture themselves living there from the moment they arrive. If you’re considering improvements before selling, talk with us before deciding how to pay for them. Depending on your situation, you may have options for using the equity you’ve built in your home.
2. Decide whether you need to sell before you buy.
Finding your next home before your current one sells can leave you with a tough decision: Do you wait and risk missing out on the home you want, or move forward before your current home sells? Buying first can also raise another important question: How will you manage the financing until your current home sells? The good news is a Bridge Loan could help you meet your timeline.
A Bridge Loan allows qualified homeowners to use the equity in their current home to help purchase their next home before their existing home sells.
That means you may be able to:
- Buy your next home before your current home sells.
- Use the equity you've already built to help finance your move.
- Make a stronger, non-contingent offer on a new home.
- Simplify the transition between homes.
- Make interest-only payments for a limited time while your current home is on the market.*
- Move to one simple monthly payment after your home sells.
Every situation is different, which is why our mortgage team takes the time to understand your goals and help you determine what option makes the most sense for your situation.
3. Put your home equity to work.
If you're choosing to stay in your current home until it sells, you may still have options to help cover repairs, improvements, or other expenses.
For example, a Home Equity Line of Credit (HELOC) may allow qualified homeowners to borrow against the equity they've built. That can provide added flexibility while preparing a home for sale or waiting for the right buyer.
Before borrowing, it's important to consider how additional costs fit into your budget. We're here to help you understand the pros and cons so you can make a decision that feels right for your financial journey.
4. Talk with us before you feel stuck.
You don’t have to wait until your home has been sitting on the market for months to start exploring your options.
If you're thinking about buying your next home while selling your current one, contact a CommunityAmerica mortgage loan officer. We'll talk through your goals, answer your questions, and help you explore financing options that may be available.
Because sometimes, the next step isn't waiting for the “For Sale” sign to come down, it's about having a plan that helps you take the next step with confidence.
Ready to explore your options?
Schedule a meeting with a CommunityAmerica Mortgage Advisor by visiting your nearest branch or calling 913.905.3799. We're here to help every step of the way.
*Bridge Loan financing is subject to underwriting approval, credit qualification, property eligibility, and program guidelines. Interest-only payments do not reduce the principal balance during the interest-only period. Terms and conditions are subject to change without notice.
